SARS tax invoice requirements: a checklist for full and abridged tax invoices
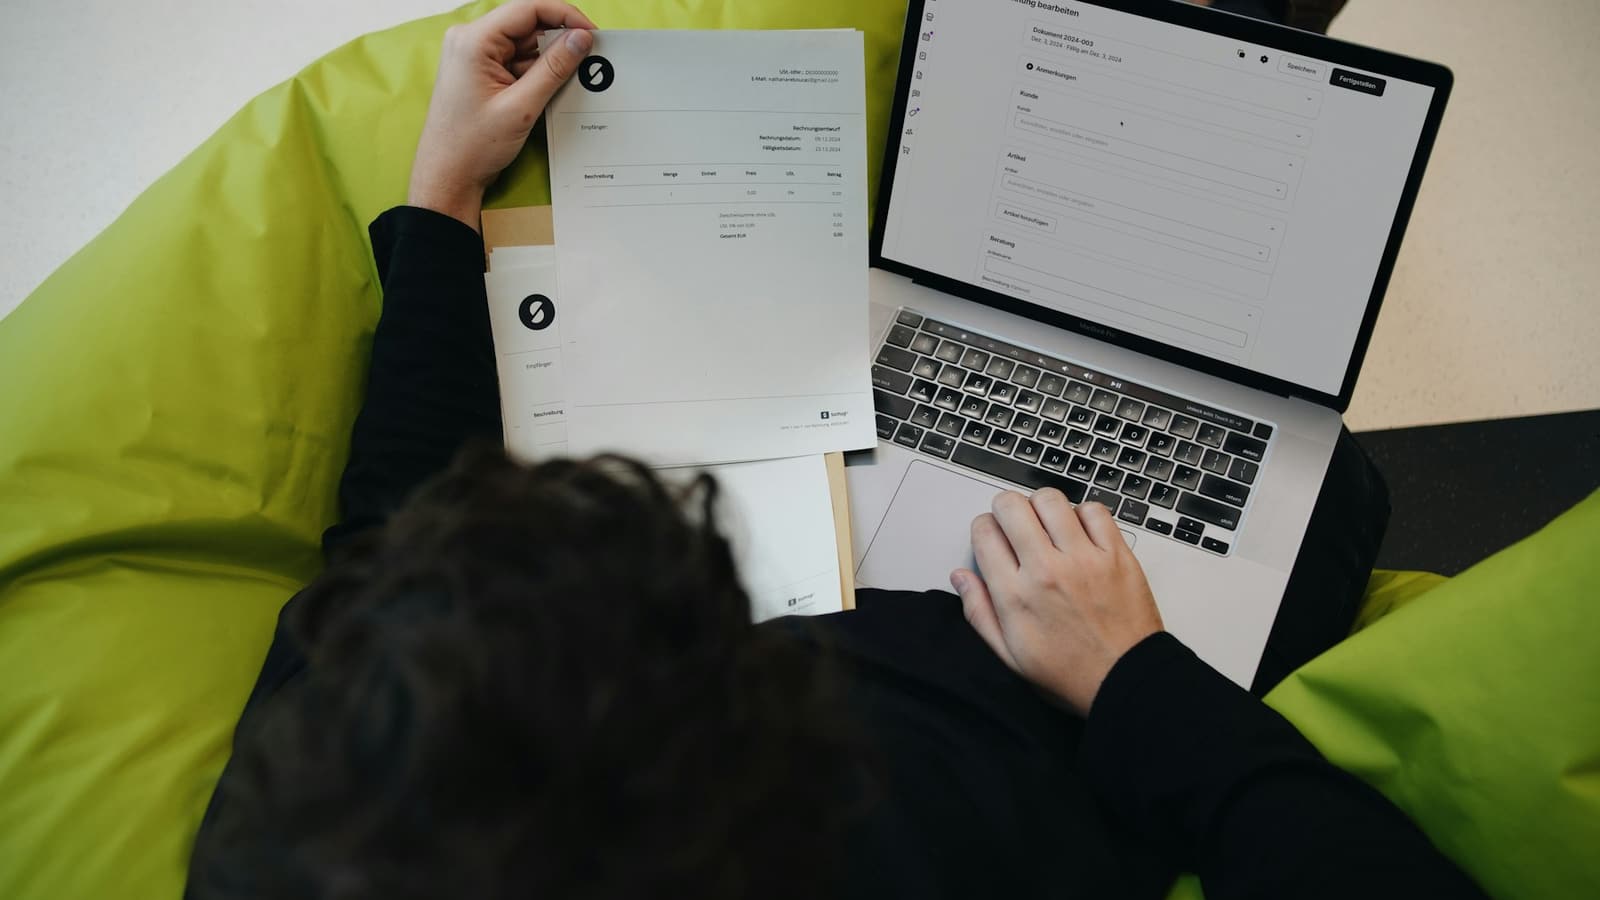
A tax invoice is the document that lets your customer claim back the VAT you charged them. If it is missing a required detail, SARS can refuse their input tax claim, and your customer will come back to you for a corrected invoice. Getting the layout right once, in your accounting software, saves that conversation forever.
Full or abridged: the R5 000 rule
| Invoice value, including VAT | What you issue |
|---|---|
| More than R5 000 | A full tax invoice |
| R5 000 or less | An abridged tax invoice is enough |
Only VAT registered vendors may issue a tax invoice, and you must issue it within 21 days of the supply, or within 21 days of the customer asking for it.
What a full tax invoice must show
- The words "tax invoice" in a prominent place.
- Your name, address and VAT registration number.
- The customer's name, address and VAT registration number, where the customer is registered.
- A unique serial number and the date the invoice was issued.
- A full and proper description of the goods or services. A code or "as per quote" is not enough.
- The quantity or volume supplied.
- The value of the supply, the VAT charged and the total including VAT. Or the total including VAT with a statement that it includes VAT at 15%.
What an abridged tax invoice must show
- The words "tax invoice".
- Your name, address and VAT registration number.
- A serial number and date of issue.
- A description of the goods or services.
- The value of the supply, the VAT and the total, or the total including VAT with a statement that VAT is included.
The customer's details are not required on an abridged invoice. SARS Binding General Ruling 27 confirms that the recipient's name and VAT number are not needed where the consideration does not exceed R5 000.
Credit notes and debit notes
When the price changes after the invoice, for example a return or a discount, issue a credit note or debit note rather than editing the original invoice. It needs the words "credit note" or "debit note", your and the customer's details, the date, a reference to the original invoice, a description of the reason and the VAT adjustment. Editing an invoice that is already in a filed VAT period is one of the most common causes of VAT201 errors.
Mistakes that cost input tax
- Leaving off the customer's VAT number on an invoice above R5 000.
- Describing the work as "services rendered" with no detail.
- Reusing or skipping invoice numbers, which breaks the serial sequence.
- Issuing a tax invoice before you are registered, or charging VAT when you are not a vendor.
- Sending a quote or pro forma and treating it as the tax invoice.
- Losing the supplier invoices behind your own input tax claims. SARS can ask for them for five years.
Are PDF and electronic invoices valid?
Yes. An emailed PDF tax invoice is valid as long as it contains every required detail, and you may keep records electronically. SARS is also preparing a formal electronic invoicing system, but it is not compulsory yet and existing invoice rules still apply. Our guide to e invoicing in South Africa explains the timeline.
Questions people ask
Products in this guide
Xero
Cloud ledger with bank feeds, VAT returns and over a thousand connected apps.
Reviewed by ToolveldFrom
R485/moincl VAT
Sage Accounting
Cloud accounting from the company behind Pastel, with local support and VAT201 built in.
Reviewed by ToolveldFrom
R270/moincl VAT
Zoho Books
Cloud accounting with a free plan, South African tax settings and rand pricing.
Reviewed by ToolveldStarting price
Free
Visit website links go straight to the vendor and earn us nothing. How we make money
Get the next guide in the monthly brief
One email a month. Unsubscribe with one click.
Keep reading
Accounting
Best accounting software in South Africa for 2026, with prices in rand
6 min read
Accounting
Sage vs Xero in South Africa: which accounting software should you choose?
4 min read
Accounting
Free accounting software in South Africa: what you really get in 2026
4 min read